India. Let’s financially equip gig workers
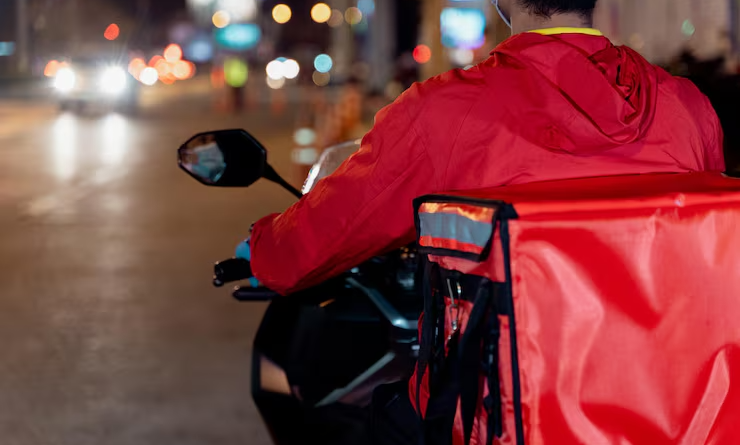
A delivery rider is paid through an app, buys his fuel and sends money home via UPI, and can tell his customer rating to the last decimal. Yet he might only quote what the platform paid him rather than what he makes, and merely guess about any insurance coverage. In other words, he is thoroughly banked, yet unable to comprehend his own finances fully and maximise financial well-being.
This gap in India’s gig economy needs policy attention. A National Centre for Financial Education survey found only 27% of Indian adults are financially literate. For a salaried worker, provident fund, insurance, and a payslip absorb much of the financial-management burden. But gig workers need to manage all three themselves.
A study by Dvara Research in Bengaluru found platform workers grossing Rs 35,075 a month and spending Rs 18,470 on fuel, maintenance, and other running costs. Most workers perceive the gross income as net. The Economic Survey 2025-26 records about 40% of gig workers earning below Rs 15,000 a month. Of 11 the platforms assessed in the Fairwork India ratings for 2024, only two could evidence workers earning the local minimum wage once costs were deducted.
The behavioural evidence supports the financial literacy deficit in gig workers. A study by LEAD at Krea University found 62% lacked emergency fund, and close to half had no insurance. A 2024 survey across 40 cities by Borzo found 65% lacking life insurance, 77% holding no mutual funds, and 61% being unable to state the income tax slabs. Two-thirds of gig workers had never filed a return. Only 20% earned Rs 2.5 lakh to Rs 5 lakh annually. For ride hailing services, while GST is managed by the platform, the workers are supposed to monitor their tax liabilities themselves. Lack of financial knowledge can result in self-inflicted exclusion from credit.
It has also become a constraint for existing schemes. The Atal Pension Yojana crossed 900 million gross enrolments in April; it pays Rs 1,000-5,000 a month for those aged 60 years or above. The PM Shram Yogi Maandhan similarly offers Rs 3,000. Registration on e-Shram is now the gateway to labour code protections. Yet by June, against an estimated 12 million gig workers and a Budget commitment to cover roughly Rs 1 crore, the labour ministry put the number registered at between 1 and 1.2 million.
Kenya offers a warning signal. By 2024, 84.8% of Kenyan adults had access to formal financial services compared to 26.7% in 2006. However, the FinAccess surveys, held every two to three years, revealed that only 18.3% were financially healthy. Inclusion produces borrowers. India’s instant loan apps are advertising to precisely this demographic.
Platforms record every trip, incentive, and deduction. A monthly statement in the worker’s language, setting out gross earnings, work-related costs, and net take-home, would hand millions of people data they currently lack. A worker who can see his net income can plan around it.
The government or NGOs can make a short financial capability module a condition for aggregator registration in the workers’ own language. Financial education cannot be an induction exercise; it has to travel alongside working life cycles. Platforms can use short, vernacular, mobile-first modules, interactive simulations, and gamified learning to explain budgeting, insurance, pensions, mutual funds, credit, taxation, and digital fraud. Workers should receive timely nudges when they get an incentive, take a loan, make a large withdrawal, or become eligible for a government scheme, directing them to the regulated financial product or official source. Periodic financial-literacy camps at delivery hubs, transport centres, and gig-worker congregation points, supported by banks, regulators, insurers, and pension providers, can complement in-app learning. Four topics carry the most immediate value: budgeting on an income that changes weekly, the difference between gross and net, how to enrol in a pension and an insurance scheme, and why an instant loan app quoting a daily rate is the most expensive money they will borrow.
Read more @financialexpress