Norway tops retirement ranking as inflation, debt fuel financial anxiety
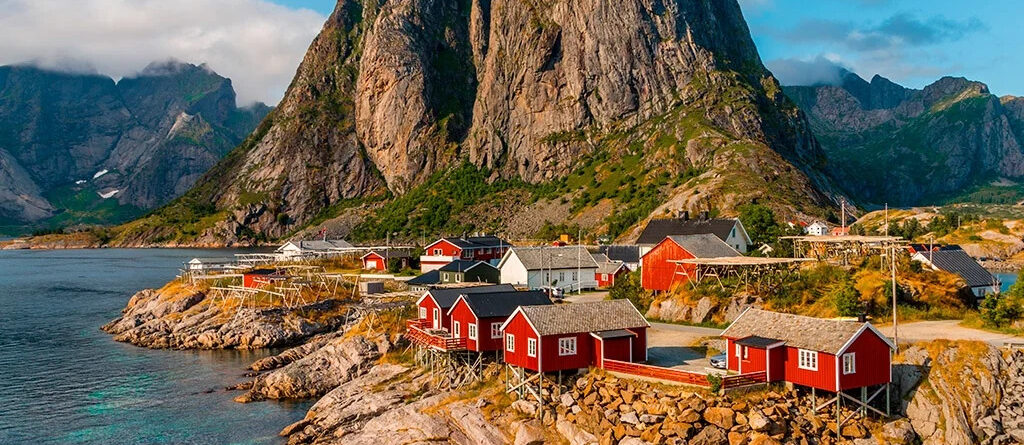
Norway has held on to the top spot in a global measure of retirement security, even as inflation, government debt and aging populations make preparing for retirement harder in much of the world.
The country ranked first for a second consecutive year in Natixis Investment Managers’ 2026 Global Retirement Index, which compares retirement conditions across 44 countries.
Norway scored 83%, followed by Ireland at 81%. The Netherlands jumped from sixth to third with 79%, its highest position since the index was introduced. Switzerland fell one place to fourth and Denmark stayed fifth.
Australia was sixth and Germany seventh. Luxembourg moved up to eighth, while Iceland recorded the biggest fall among the top 10, dropping five places to ninth as higher unemployment hurt its material-wellbeing score. Czechia rose one place to 10th.
Natixis developed the index with CoreData Research and draws on 18 indicators covering four areas: finances in retirement, material wellbeing, health and quality of life. The 44 countries include IMF advanced economies, OECD members and the BRIC nations of Brazil, Russia, India and China.
Norway’s lead rests largely on strong employment, relatively even income distribution, healthcare and quality of life.
Retirement finances have traditionally been a weaker part of its score. Natixis has previously pointed to the country’s high tax burden and the financial demands of an aging population, even as Norway performs strongly on most of the index’s other measures.
The country rankings tell only part of this year’s story. Across the investors surveyed by Natixis, 68% said inflation was reducing the future value of their savings and 66% said higher everyday costs meant they were saving less. Nearly three-quarters, 72%, worried that rising government debt could eventually mean lower retirement benefits.
The responses come from Natixis’s 2025 Global Individual Investor Survey, conducted by CoreData Research among 7,050 investors in 21 countries and used in this year’s retirement study.
A growing number also believe they will have to carry more of the cost themselves. Seventy-eight percent said responsibility for funding retirement increasingly falls on the individual, compared with 67% a decade earlier.
For 43%, the prospect looks daunting enough that they said securing a comfortable retirement would take a “miracle.”
Natixis argues that many retirement systems were designed for a different labor market, when careers tended to be more predictable, workers often stayed longer with one employer and retirees generally spent fewer years drawing retirement income.
Those conditions have changed. People are living longer, workers change jobs more frequently, and gig work, self-employment and part-time employment account for a larger part of working life.
That creates problems for retirement arrangements tied closely to long spells with a single employer. Aging populations also mean more retirees relative to the working-age population that supports government pension systems.
India illustrates the challenge. The country is one of the 44 covered by the index and has struggled near the bottom of the ranking in recent years, in part because retirement protection remains uneven across a workforce dominated by informal employment.
Natixis estimated in its 2025 report that about 415 million people, or 86% of India’s workforce, were employed informally. It highlighted the government’s e-Shram database and the Pradhan Mantri Shram Yogi Maandhan pension scheme as attempts to extend social-security and retirement coverage beyond regular salaried workers.
Coverage has expanded since then. Government data released in May showed more than 21.7 million subscribers in the National Pension System and 89.6 million enrolments in the Atal Pension Yojana as of March 31, 2026.
The United States illustrates some of those pressures. That country fell three places to 24th in the 2026 index, down from 14th a decade ago. Its ranking for finances in retirement dropped eight places in a single year to 18th.
Among US investors surveyed by Natixis, 76% said they expected rising government debt eventually to reduce retirement benefits.
Healthcare presents another problem. The US spends more per person on healthcare than any other country covered by the index but ranks 25th on its health measure.
Thirty-five percent of US investors said they feared going broke paying for healthcare and long-term care in retirement. The global figure was 24%.
The countries near the top do not follow a single model. Norway, Ireland, the Netherlands and Switzerland arrive there through different combinations of income, employment, healthcare, government finances and quality of life.
Policymakers are also taking different routes, though Natixis sees much of the recent reform effort clustering around three objectives.
Governments are trying to bring more workers into retirement plans, improve the amount people accumulate and make saving more automatic through measures such as automatic enrollment and contributions.
That shift reflects how the retirement equation is changing. Longer lives require savings to last longer, while inflation determines how much those savings will ultimately buy. Public debt can constrain governments, and less predictable careers can make workplace retirement plans harder to maintain.
The index attempts to capture those pressures rather than simply identify pleasant places to spend old age. Its rankings measure how well countries are positioned to support retirement security when responsibility is increasingly divided among governments, employers and individuals.
Read more @pressinsider