US. 10 Million Seniors Live in Poverty—Even as They Hold Trillions in Housing Wealth
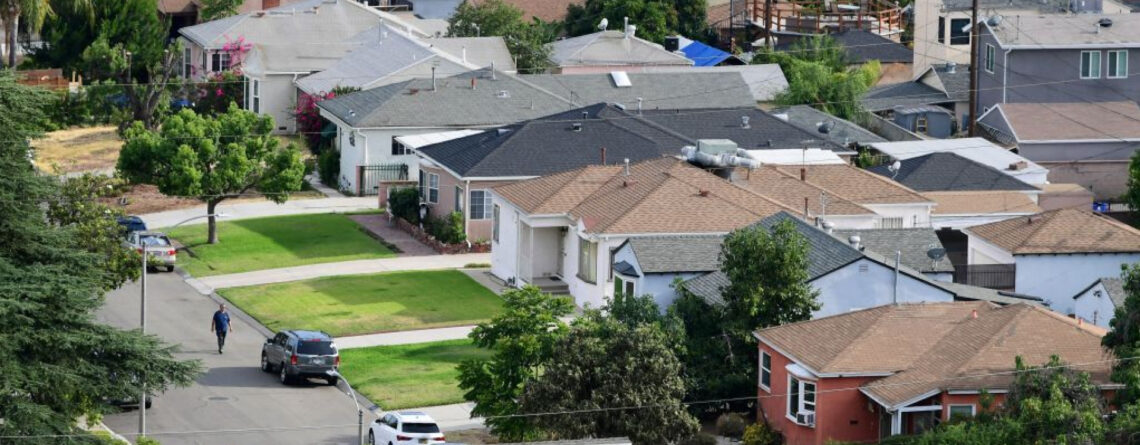
Older Americans are sitting on enormous amounts of housing wealth. At the same time, poverty among them is rising.
About 10 million Americans aged 65 and older lived in poverty in 2025 under the Supplemental Poverty Measure, according to a new AARP Foundation analysis of U.S. Census Bureau data. Their poverty rate reached 15.4%—the highest of any age group.
The findings clash with a familiar story about aging in America: Older generations have accumulated tremendous wealth, much of it in their homes, and are expected to pass trillions of dollars to their heirs over the coming decades.
“There are two things at play here,” Berner says. “First, those aggregated wealth numbers skew heavily toward high net worth seniors. Seniors who don’t own homes are much more likely to face poverty conditions, so both situations can be true for different subsets of the senior population.”
Homeownership itself doesn’t necessarily resolve the contradiction, either.
“Second, even among homeowning seniors, their housing wealth is illiquid,” Berner says. “It can’t pay for groceries or utilities unless the home is sold or borrowed against, so many seniors end up house-rich and cash-poor.”
The housing shortage can trap older homeowners, too
The gap between the government’s two poverty measures helps illustrate Berner’s point.
Under the official poverty measure, 9.8% of adults 65 and older—or about 6.4 million people—were poor in 2025. Under the Supplemental Poverty Measure, which accounts for expenses like out-of-pocket medical costs, the rate was 15.4%, or roughly 10 million people.
“The biggest advantage the SPM offers is insight into out-of-pocket medical expenses, which affect seniors at a high rate even after Medicare benefits are applied,” Berner says. “Seniors dealing with medical issues can easily become cash-strapped, and it’s important to include this in the analysis.”
And poverty figures alone don’t capture the depth of the financial strain.
Over half (53%) of older adults living alone and a quarter (25%) of older couples had incomes below what they needed to cover basic expenses in 2025, according to the University of Massachusetts Boston’s Elder Index—an increase of 5 and 4 percentage points, respectively, since 2022.
Jan Mutchler, director of UMass Boston’s Gerontology Institute, has described the distinction this way: “Our goal with the Elder Index is to move the financial security conversation toward adequacy rather than destitution.”
And housing is a growing part of that conversation.
The income needed to meet basic expenses rose from $36,300 in 2022 to $39,396 in 2025, for a single older homeowner with a mortgage—higher housing costs accounted for roughly two-thirds of that increase.
Even homeowners without a mortgage weren’t insulated. Their housing expenses rose nearly 14% over that period, as the costs of homeownership climbed.
Across homeowners, property taxes rose 31% between 2019 and 2025, while average monthly homeowners insurance premiums jumped 72%, according to Harvard University’s Joint Center for Housing Studies’ 2026 State of the Nation’s Housing report. Median housing costs for owners who held their homes free and clear rose 35% between 2019 and 2024, compared with a 23% increase in homeowner incomes.
Read more @realtor