July 2020

Protecting South Asia’s poor and vulnerable against COVID-19

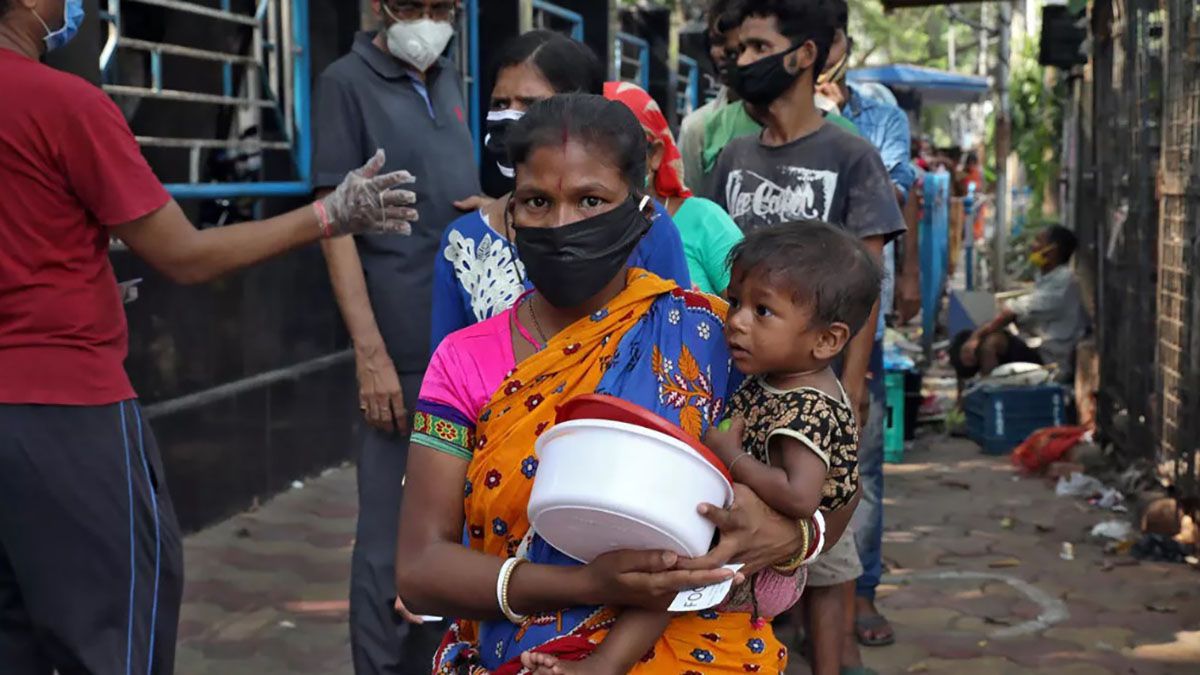
By Lynne Sherburne Benz, Stefano Paternostro, Zaineb Majoka When India went into lockdown in late March as a result of COVID-19, one of the country’s biggest priorities was to ensure access to food. As millions risked starvation, the government mobilized its existing Public Distribution System (PDS) to give away food rations to over 800 million people, thus averting a catastrophic food crisis. As the coronavirus spreads exponentially across South Asia, food insecurity is just one of the many challenges...
June 2020

‘Alarming number’: Boomers struggle to save enough for retirement, survey finds

Many baby boomers don’t have nearly enough money to retire. The median amount they have saved for retirement is $144,000, according to a recent survey from Transamerica Center for Retirement Studies, a figure that should be a “call to action” for boomers, said one financial expert. “When we think about it, $144,000 to last in retirement that could be 20 or 30 years just isn’t going to go very far,” said Catherine Collinson, CEO and president of the Transamerica...

Wealth Distribution and Retirement Preparation Among Early Savers

By: Alice Henriques, Lindsay Jacobs, Elizabeth Llanes, Kevin B. Moore, Jeffrey P. Thompson. This paper develops a new combined wealth measure using data from the Survey of Consumer Finances, by augmenting data on net worth with estimates of defined benefit (DB) pension wealth and expected Social Security wealth. We use this combined wealth concept to explore retirement preparation among groups of households in their pre-retirement years (40-49 and 50-59) and also to explore the concentration of wealth. We find...

UK. Workplace pension income rises by more than a third

Income from workplace pensions in the UK has risen by more than a third in just 10 years, analysis by financial services firm Equiniti has revealed. The findings show that average occupational pension income rose from £121 to £167 a week between 2008/09 and 2018/19, representing an increase of 38%. This is despite other sources of income remaining broadly flat or negative, with occupational pensions now accounting for 30% of total average pensioner income, up from 24% in 2008/09. ...

Can Low Retirement Savings Be Rationalized?

By John B. Shoven, Sita Slavov, John G. Watson Simple presentations of the life cycle model often suggest a constant level of real consumption in retirement. Similarly, financial planners commonly suggest that people save for retirement in such a way as to enable them to maintain a level retirement standard of living equal to their standard of living while working. However, constant consumption with age is only optimal under the precise and unlikely condition that the subjective rate of...

May 2020

The Effect of Workplace Pensions on Household Saving: Evidence from a Natural Experiment in Taiwan

By Tzu‐Ting Yang Population aging causes financial imbalances in pay‐as‐you‐go public pension programs. To remedy this problem, while ensuring the adequacy of retirement savings for employees, many countries complement or substitute public pensions by regulating their workplace pensions. This article exploits a pension reform in Taiwan that has mandated, since 2005, that all private‐sector employers contribute at least 6 percent of an employee's monthly wage to an individual pension account. I use workers in the unaffected sectors as a...

Integrating Social Insurance and Social Assistance Programs for the Future World of Labor

By Robert J. Palacios, David A. Robalino Given the prevalence of informal labor, most countries have combined contributory social insurance programs (pensions, unemployment benefits, and health insurance), with non-contributory insurance programs and several types of "safety nets." All of these programs involve different types of subsidies and taxes, sometimes implicit. Because of design problems and the lack of coordination/integration between programs, these subsidies/taxes tend to cause four problems: 1) they can reduce incentives to contribute to mandatory insurance programs...

US. The No.1 reason people make early withdrawals from retirement funds may surprise you

By John Anderer Retirement is the prize at the end of the work marathon. Any financial advisor or accountant will tell you it’s a good idea to start saving for retirement as early as possible, and the average working adult spends decades adding money, little by little, to his or her retirement fund. When the time comes, that money will be spent on leisure, fun, and everything else we can’t do while working full time. Now, you’re not supposed to touch...

Australia. Universal pension for all: Retirees call for tax and income reform

Every retiree would get at least a part pension under a plan being considered by seniors' groups amid concerns the coronavirus pandemic's effect on key income streams is leaving many older Australians cash poor and increasing the number living in poverty. Seniors organisations are pressing the Morrison government to look at a massive overhaul to the pension system that would also take into account possible changes to tax concessions, such as franking credits, as a way to pay for...

The 2018 Pension Adequacy Report: current and future income adequacy in old age in the EU

By European Commission The 2018 edition of the triennial Pension Adequacy Report analyses how current and future pensions help prevent old-age poverty and maintain the income of men and women for the duration of their retirement. Volume I is devoted to comparative analysis of pension adequacy in the EU- 28. It examines the current living standards of older people and how they are shaped by pension systems, proceeds with an overview of recent pension reforms and concludes by analysing...