September 2026

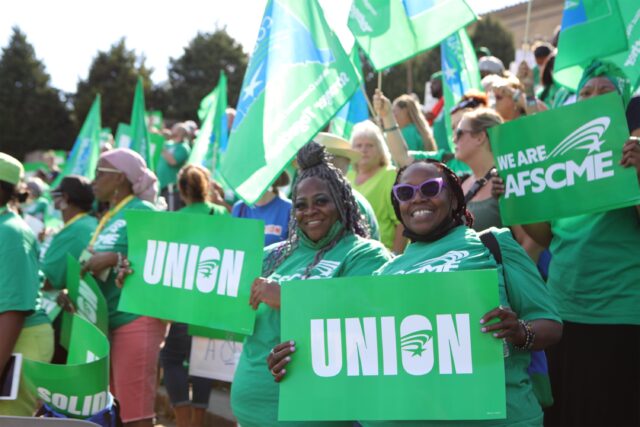
US. AFSCME and labor allies say ‘no’ to crypto in our pensions

AFSCME, other labor unions and pro-retiree allies are fighting back against the cryptocurrency lobby’s efforts to pass a dangerous measure called the CLARITY Act. This bill would make it easier for highly unstable and unregulated cryptocurrency to infect millions of workers’ pensions and 401(k) accounts – even if the workers don’t intend to invest in crypto. The CLARITY Act is a serious threat to our retirements and a threat to our entire economy. By making it easier for the crypto industry...
US. Why Pensions Still Provide Key Income for Many Retirees Even as Access Declines

Traditional pensions, where employers guarantee their workers a fixed monthly paycheck for life in retirement based on their salary and years of service, are widely considered a thing of the past. But the reality is more complicated. While these highly sought-after defined benefit (DB) plans are no longer an option for most of today's workers, for retirees, they remain a common source of income. Pensions Are Much Less Common for Workers Today Only 29% of American workers have an employer-sponsored DB pension,...

Pensions and Turbulence: Automatic Adjustment, Risk, and Fairness in Long-Term Pension Design

By Peter A. Diamond Public pension systems are long-term social contracts operating under persistent economic, demographic, and political uncertainty. Periods of turbulence, marked by financial shocks, changes in longevity, and shifting labour markets, test the capacity of pension institutions to adapt while maintaining adequacy, equity, and legitimacy. Building on earlier joint work on pension economics and reform with Nicholas Barr, this chapter analyses the role of automatic and semi-automatic adjustment mechanisms in public pension design. Drawing on comparative experience from...

US’s Solo Aging Crisis Is Here

Most people spend decades planning for the financial risks of retirement. Almost no one plans for the social ones. Yet the risk that derails the final chapter of life is rarely running out of money. It is running out of people. Roughly 28% of Americans age 65 and older now live alone, according to Census and KFF Health News data, up from about 10% in 1950. More than 38 million Americans of all ages currently live alone, the highest share...

US. Explaining the Rise in Alternative Investments in Public Pension Plans

In recent decades, public pension plans in the United States have changed how they take on risk. At the turn of the century, their risky investments were primarily in public equities, whereas alternative assets – like private equity, real estate, and hedge funds – accounted for just 14 percent of all risky investments. By 2021, the share of risky assets in alternatives had grown to 39 percent. Equally interesting, the adoption of alternatives has varied enormously across plans. What...

Global pension asset allocations and debt markets

By Ding Ding, Xiang Fang, Bryan Hardy & Karen K. Lewis The pension sector is an important investor group in global financial markets and a key holder of government and corporate debt. This article examines the evolution of pension fund asset allocations around the globe and documents two important structural changes. First, pension investors have shifted portfolio share allocations away from fixed income securities. This trend is robust across Defined Contribution (DC) and Defined Benefit (DB) programs as well as...

Redistribution through Taxes or Pensions? Optimal Income Tax and Pension Progressivity

By Burkhard Heer & Mark M. Trede We develop a medium-scale overlapping-generations model with endogenous labor supply and skill premium to study optimal income redistribution using progressive labor income taxes and pensions. The model is calibrated to the four countries USA, Great Britain, Italy and Germany which differ substantially in their tax and pension systems, demographics, and skill shares among workers. Optimal pension benefits are proportional to lifetime contributions in all four countries, while the optimal degree of income tax...

Pensions from Capital: How Pension Funds in the United States, Japan and Europe Invest -and What Private Investors Can Learn from Them

By Roland Rupprechter This paper examines the pension funds of the large industrial countries — with more than USD 68 trillion between them, the heaviest group of investors in the world. It compares how funded retirement provision is organised in the United States, in Japan and in Europe: how state, occupational and private provision differ, who grants which tax advantages to whom and at what level, and why equity quotas diverge so widely across regions — from 25 per cent...

US. DC plan sponsors struggle to define retirement readiness: WTW

A recent survey of more than 550 US employers by WTW has exposed an uncomfortable truth at the centre of defined contribution plan governance: a large majority of plan sponsors have no formal definition of what retirement readiness means for their workforce. “You can't prove that your plan works if you haven't defined what working actually means,” said Chris West, senior managing director and DC strategy leader at WTW. “Employers are facing a retirement readiness gap and that pressure is...

Análisis Comparativo de los Sistemas de Pensiones en Colombia y Estados Unidos

Por Daniela Lara Henao, Juan Pablo Cardona Castaño, María Ruby Restrepo Betancourt & Sindy Viviana Giraldo Arcila  Los sistemas pensionales son un pilar fundamental en la seguridad social y económica de las personas en su vejez. Colombia y Estados Unidos han implementado dos sistemas distintos con características y desafíos propios, sin embargo, aunque ambos países cuentan con sistemas de pen-siones con enfoques y estructuras diferentes, también enfrentan desafíos similares en términos de cobertura, nivel de beneficios y sostenibilidad financiera. Teniendo...